Patrick Coffey 00:00
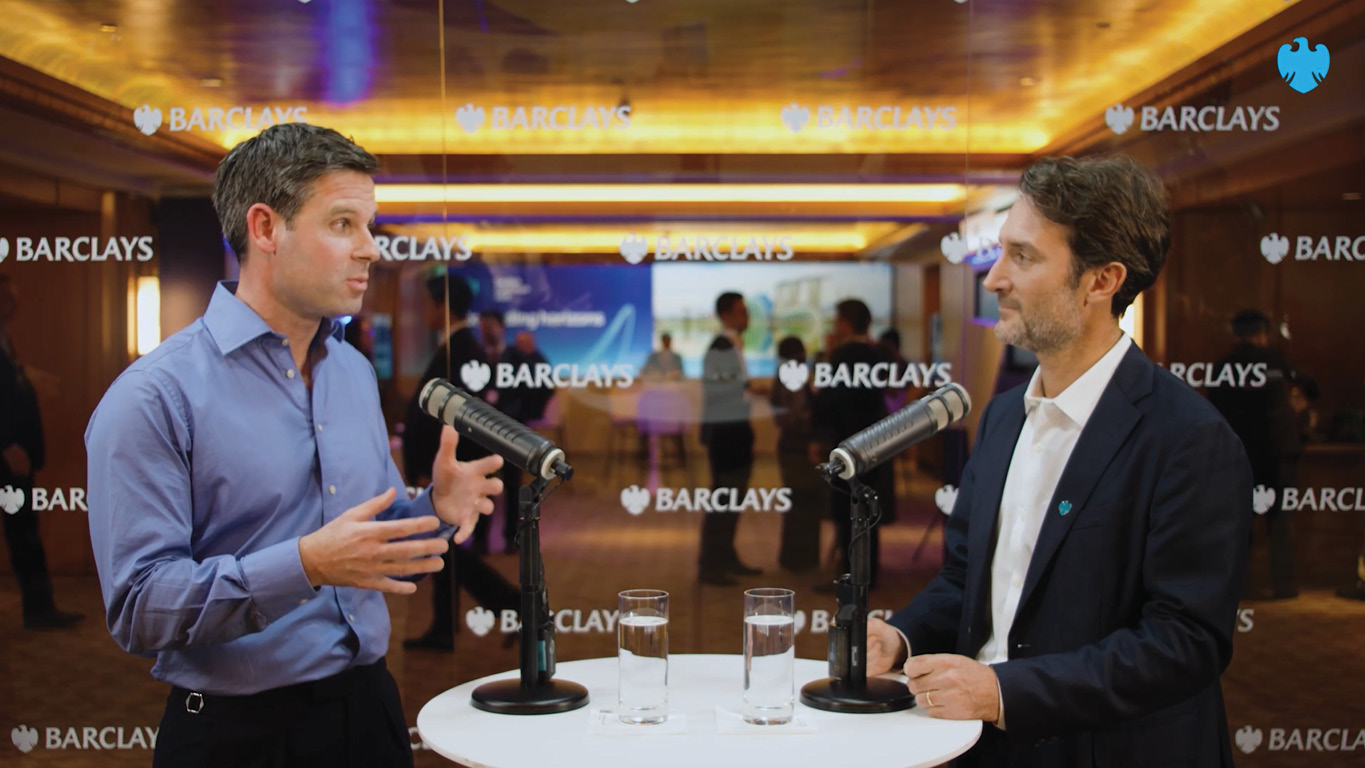
Think about what's driving your investments right now. AI, currencies, interest rates, geopolitics. At the centre of all of those stories is what's happening here in Asia. I'm Patrick Coffey. This is the Barclays Brief. It's Thursday, the 22nd of October and we're live from Singapore at the Barclays Asia Forum. I'm excited today to talk to JF Mastrangelo, our Head of APAC Markets. JF, thank you so much for being with me today and peeling yourself away from a very busy day at the forum.
JF Mastrangelo 00:30
Hey, Patrick, it's great to have you here in Singapore.
Patrick 00:32
Yeah, it's great. So very busy day. We've got over 1,000 investors and clients here today. What's the buzz? What are people talking to you about? What are investors worried about?
JF 00:40
Look, most of the Asian investors' questions revolved around three main themes. One is AI CapEx and revenues, second is oil prices and central bank policies, and third is fiscal deficits and long duration. And the reality is Asia sits at the centre of all those three themes. Why? Because Asia is the leading manufacturing hub of the world's AI CapEx. Secondly, the region imports a significant share of its energy. And thirdly, the region is mostly sensitive to changes in global liquidity. Now, today if you ask me, I would say that the main question is the AI CapEx. It's really the $1 trillion question that animates people's minds today.
Patrick 01:19
Yeah, definitely. I mean, that's what everyone's talking about here. Let's talk about the obvious trades. Korea and Taiwan are where I want to start because AI CapEx is on everyone's mind right now. Both markets have sold off a lot recently, but not the same as each other. Let's start with Korea. Is the sell-off enough to get investors interested? Are valuations attractive enough right now?
JF 01:40
Look, you're right to say Korea has been the epicentre of the sell-off. The largest two Korean stocks, SK Hynix and Samsung, have sold off 20 to 30% of their value since the start of October. Why is that? Their business is very cyclical based on memory prices, and they have suffered a lot from the negative AI CapEx sentiment since the start of the month. Also, we should look at the flows. The retail support has vanished since the collapse of the leverage ETF, and foreign investors have really sold throughout the year. So Korea trades on air pocket right now, leading to distressed valuations of the stocks, 3 to 4X forward P/Es, which leaves the investors interested by the value, but also wary of volatility. We have seen on some implementations through derivatives.
Patrick 02:25
OK, so derivatives are how people are playing it, but ultimately Korea is cheap, risky, and volatile. What about Taiwan?
JF 02:32
Look, Taiwan is a different story. The business model of the whole Taiwan ecosystem is to export semis that are much more tailored to end user needs compared to memory. So it's much more stable prices, and therefore much more stable investments. Now, TSMC remains the company everyone looks at because it is really the clearing house for AI CapEx. Its leading-edge manufacturing capacities of interest for everyone, you name it, Broadcom, AMD, NVIDIA, Apple, et cetera.
Patrick 03:01
OK. So let's move away from these obvious AI trades of Korea and Taiwan. Say I'm bearish on AI, and clients are becoming increasingly bearish on the AI infrastructure trade as we speak. Where in Asia should I be investing to diversify away from that risk?
JF 03:16
Many investors are going to name India here. First, the Indian IT services are obviously anti-correlated to AI growth, and typically since the start of the month, they've posted double-digit returns. Now, I tend to see India as a macro play. India has a strong population, strong demographics, and also a very high real GDP growth, more than 7% year-on-year recently. And if you want to play India growth, Indian banks are very attractive on a valuation point of view relative to history currently. They have posted large loans year-on-year growth, and some of them double digits. So somehow you don't trade India on chips, you do trade India on their domestic growth. And this is an interesting AI-agnostic investment to make.
Patrick 03:59
OK, so that's the AI-agnostic one. I always think about India through the lens of China and compare the growth rates, and the growth rates have decoupled in the last few years. As you say, very high growth in India, slower growth in China. When you look at China right now, what do you think? Because we've got low inflation, weak domestic consumption, low rates. It's a bit risky, isn't it? Is there any reason to be positive on China right now?
JF 04:22
First, you're absolutely right on the demographics. India and China currently have the same population, 1.4 billion, but one is growing, India, one is decreasing, China. So China has this ageing population problem, which explains why they are so much focussed on technology and productivity, and why they have become the leading force of robotics. China has a pattern that looks a little bit like Japan decades ago. They have this population issue, but also a large domestic savings rate, 40% of the GDP, which gets invested massively in domestic bonds. The Chinese rates are 1.6%. So what is there in China? Well, the reality while the world expects constantly Chinese consumer, the one that keeps surprising is the Chinese producer. China's exports are extremely strong. The latest print was 36% increase year-on-year, thanks to green tech and AI exports. So investors are really constructive about China exports, and therefore they are also constructive on the Yuan, maybe not against US Dollar because of hiking concerns on the US Dollar, but definitely against Euro for all the reasons we know in Europe.
Patrick 05:30
OK, so this idea that you're talking about with China reminding you of Japan a decade or so ago, that's interesting. We should talk about that another time. Let's switch to Japan because here at the Barclays Asia Forum, clients are pretty bullish on Japan, but there is of course, the potential for a lot of Japanese money to move back home. What would a meaningful repatriation of Japanese capital mean for Japanese assets?
JF 05:54
Look, first, you're right, Japan is a booming economy. It has found its way into the leading sector of AI manufacturing alongside Korea and Taiwan. And in a way, Japanese equities are really an investment on Japanese growth with an AI kicker, which is very interesting. Now to your question. This repatriation of assets is driven by one large national pension fund called GPIF, which is actually the biggest in the world. It owns $2 trillion of assets. And it is now quite consensual that they are somehow changing their allocations from US assets into Japanese assets. Japan bonds have rallied significantly on the basis of that expectation. Now to your question, what does it mean for US assets? Let's have some simple maths here. $2 trillion of assets, if you change your allocation by 5%, it's $100 billion of potential outflows from the US. If you compare that to the US Treasury buyback, for instance, it's significant. The buyback is $10 billion of buybacks per month roughly.
Patrick 06:57
OK. So finally, I've got you here. There's a big trade rotation happening in the market. What's your view in Asia? What's happening on the AI CapEx trade? What's your big picture take on how to play that as an investor?
JF 07:09
So look, first, why is AI CapEx, so important for Asia? For me, AI CapEx doesn't only create market leaders on the stock market, it creates national economic growth and wealth effect.
Patrick 07:21
Give me some examples of that.
JF 07:22
Taiwan is a $1 trillion economy, and TSMC as a company is meant to have a 2026 earning of $100 billion, 10% of the GDP. Korea is a $2 trillion economy, and its two largest corporates that we mentioned before will deliver $400 billion of earnings. That's 20% of the GDP. Those are massive numbers that influence not only those companies, but the whole country, the whole society, and the whole macro of those countries.
Patrick 07:51
OK, so those wealth effects will benefit the companies. How should we kind of end this in terms of thinking about the big picture on the AI CapEx trade from here then?
JF 07:58
Look, at the moment, there are the optimistic and the pessimistic on AI CapEx. I tend to sit on the optimistic side. Why? Those are the large picture numbers that help me think about it. The world has more than $100 trillion GDP per year. Corporates returned revenues of more than $30 trillion per year. Is the world going to find a way to pay for AI CapEx for $1 or $2 trillion per year? I would tend to think so. We've discussed about AI CapEx today, but there is so much more to Asia than the, the CapEx. And typically, let's all remember, Asia hosts 60% of the world's growth and also 60% of the population. So there will be many more opportunities across equities, rates and credit, but for that you have to come back next year.
Patrick 08:43
Well, I'll very happily come back. This is an amazing, amazing conference, and it's been great to catch up. JF, thanks for your time.
JF 08:48
Thank you, Patrick.
Patrick 08:49
So it's been great to talk to JF today, and we're in the midst of an AI rotation in markets right now. But standing here in Singapore at the Barclays Asia Forum, we're reminded that markets like Taiwan, Korea, Japan, offer different variations on the AI theme. Of course, many people out there will be bearish on AI. I thought JF's insights on India were particularly interesting around diversifying risk away from the typical AI markets. And finally, when considering investing in Asia, it's just so important to remember how nuanced this market is. So for global investors, they can't keep their eyes away from Asia. Thanks a lot for listening to the Barclays Brief. We'll be back next week with a very special episode, and until then, do hit subscribe.