Podcast: US Rathes: Higher for longer
With the US 10-year Treasury yield reaching 5%, hear Barclays Head of US Rates Trading, Dan Orlando explain why AI and infrastructure spending are reshaping the impact of higher rates on the US economy.


Investment Bank
Barclays Live
BARX
BarclaysME
RESEARCH | THE FLIP SIDE | EPISODE 87
Do debt managers or markets set the price of long bonds?


17 Sep 2026


To subscribe, please visit Apple Podcasts or Spotify
SUBSCRIBE
Around the globe, developed economies' government bond yields are climbing. In response, debt managers are reshaping how they borrow, shortening issuance and buying back longer-dated debt in an effort to reduce the duration investors must absorb. But can government debt managers truly influence long-term yields, or do markets ultimately have the final say?
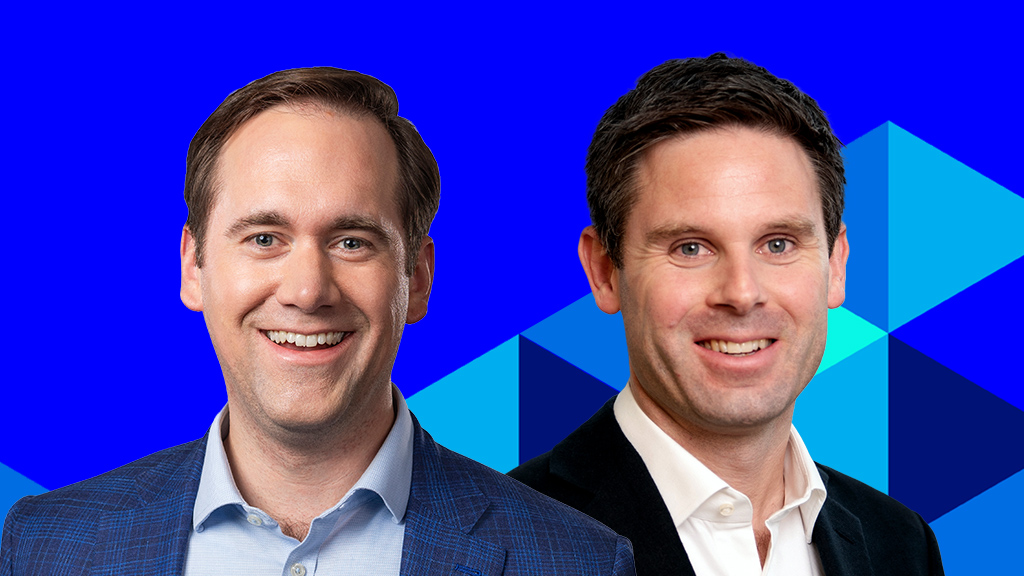
In this episode of the Flip Side, Brad Rogoff, Global Head of Research at Barclays, and Anshul Pradhan, Head of US Rates Research, debate whether bond supply is becoming a more powerful driver of markets as private investors absorb an ever-growing share of government debt.
Together, they examine shifting supply, the changing long bond investor base and the growing issuance for long-duration capital from non-government sources. As debt managers rethink how they finance large deficits, the debate explores whether they can influence the price of duration, even if growth, inflation and policy expectations ultimately determine the direction of yields.
Listeners can learn more about this topic:
Clients of Barclays Investment Bank can read our latest reports by logging in to Barclays Live:
With the US 10-year Treasury yield reaching 5%, hear Barclays Head of US Rates Trading, Dan Orlando explain why AI and infrastructure spending are reshaping the impact of higher rates on the US economy.
Brad: Good morning and welcome back to The Flip Side. I’m Brad Rogoff, Global Head of Research at Barclays, and today I am joined by Anshul Pradhan, our Head of US Rates Research. Anshul was a pretty easy choice for this month’s episode considering the recent volatility in the Treasury market. What I would love to discuss is a question that has moved from the technical margins of the bond market to the center of the debate: can governments lower long-term borrowing costs simply by changing how they borrow? That work for you, Anshul?
Anshul: You know I am happy to debate anything about bond market technicals.
Brad: Let me set the backdrop with what has been going on and not just in the US. Government debt managers everywhere have been busy. The US Treasury has leaned on bills and stepped up long-end buybacks. Japan has cut super-long issuance. The UK has repeatedly moved issuance away from the long end. Euro-area issuers have also shortened what they sell. Seems like we have a trend?
Anshul: We do. At the simplest level, they are trying to reduce the amount of duration the market has to hold. If investors look reluctant to own long-dated bonds, one answer is to issue fewer of them and fund more of the borrowing at the front end, in bills. Less duration out the door, less term premium to pay. That's the theory.
Brad: So, for our listeners, term premium is really just the extra compensation investors demand for locking their money up for a long time and accepting that the future may not unfold the way they expect?
Anshul: Exactly. The more uncertainty investors see around inflation or policy rates, the more compensation they may demand to hold long-term bonds.
Brad: And debt managers are putting that theory about duration into practice. The US, the UK, Japan and euro-area issuers have all arrived at versions of the same response. When several governments independently decide that the maturity of what they issue deserves this much attention, that tells you something. They believe supply affects the price of their debt. I take that revealed preference seriously.
Anshul: I'd take it seriously too, up to a point. That composition matters, I don't dispute. Where I hesitate is the jump from "it matters" to "it decides where long yields settle."
Brad: Start with something simple. There is no single giant investor with a bottomless balance sheet who will buy whatever a government issues. Possible buyers include pension funds, insurers, banks, reserve managers, mutual funds and hedge funds. Every one of them wants something different. A pension fund needs long bonds because it has long liabilities. A money fund would not go near them. These buyers aren't interchangeable. Call it preferred habitat if you like. To me, it's simply how the market is put together.
Anshul: I'm with you on that. Different clienteles, different maturity buckets, no argument from me.
Brad: Then take it one step further. If the buyers aren't interchangeable and none can hold an unlimited amount, how much you issue in each maturity bucket has to matter. Dealers run out of balance sheet. Hedge funds run out of financing. Pensions only need so much. Push more duration at the market and the price has to move to get it absorbed. Duration has to be held by somebody, and somebody always sends a bill. Issue less of it and the last buyer needs less convincing. That's just supply and demand.
Anshul: I agree with the mechanism. In fact, that's probably the cleanest reason issuance affects term premium. Where I'd push back is that supply mattering and supply dominating are two different things.
Brad: Meaning?
Anshul: Supply can absolutely influence yields. But long-term yields also reflect expectations for growth, inflation and the path of policy rates. Those forces can be much larger. So I agree that supply matters. The debate is about how much it matters relative to everything else.
Brad: Of course those things are part of it, but why do you think those forces are larger?
Anshul: Because they affect the biggest component of the yield. Supply mostly works through term premium. Expectations affect where investors think short rates will be over many years. If investors start believing growth will be stronger, inflation stickier, or policy rates higher than they previously thought, that can have a much bigger impact on yields than a modest change in issuance composition.
Brad: So you're really arguing about the balance between expected rates and term premium.
Anshul: Exactly. Supply can move the compensation investors demand to hold duration. But if the market is simultaneously repricing the entire path of policy rates, those effects can be overwhelmed.
Brad: But doesn't that set the bar too high? Supply doesn't need to dominate every other force to matter. If debt managers lower yields relative to where they otherwise would have been, I'd call that success.
Anshul: That's fair. The right counterfactual isn't where yields are. It's where they would have been without the issuance change. The challenge is we never observe that alternative world.
Brad: Then let's talk about where supply actually enters the equation.
Anshul: A useful starting point is to remember that a long-term yield has two broad components. One is the average path of short-term rates investors expect over the life of the bond. The other is term premium, the compensation investors demand for taking duration risk. Issuance mainly works through the second component. Reduce the amount of duration investors have to absorb and, all else equal, term premium should be lower.
Brad: But all else doesn't have to be equal for the policy to work.
Anshul: Correct. The macro factors can push yields higher while issuance decisions keep them lower than they otherwise would have been.
Brad: Which is why I think supply often gets held to an impossible standard. If yields go up after issuance is reduced, many people conclude the policy failed.
Anshul: That's a fair criticism. The question should be whether yields would have risen even more without the change.
Brad: So supply is only half of the equation, yet we usually focus on it first because it is easiest to quantify. On the demand side, the buyer base has changed dramatically. A decade ago, the Fed and foreign central banks absorbed a much larger share of the market. Today, private investors hold about three-quarters of Treasuries.
Anshul: I think that's one of the most important developments in the market. Official investors often buy for policy or reserve-management reasons. Private investors tend to care much more about valuation.
Brad: Which means supply should matter more than it used to. Every additional bond has to clear with an investor who can say no.
Anshul: So that means the investor base has become more discerning. The rise of price-sensitive investors can be an argument for why issuance matters more today than it did during the QE era, but at the end of the day these investors are price-sensitive and as I said before, supply is only one component of determining that price.
Brad: It’s only one component, but it’s about clearing the hurdle of the marginal investor. And the hurdle may be higher for another reason. For much of the post-crisis period, Treasuries were a dependable hedge against equity risk. Investors could accept a lower yield because bonds provided insurance elsewhere in the portfolio. That relationship has become less reliable. Just look at major risk-off episodes in recent years, bonds have failed to rally in each one of them.[TS2.1]
Anshul: If we are talking purely demand now, I think that matters. If duration is a dependable hedge, investors may be willing to hold it at a lower expected return. If that protection is less reliable, particularly when inflation shocks can hurt bonds and equities at the same time, investors need more compensation.
Brad: So if we drill down on just the higher term premium, it may reflect not only who is buying the bonds, but also what those bonds now contribute to a portfolio.
Anshul: Exactly. The market is asking private investors to absorb more duration at a time when its diversification value is less certain. That can raise the yield required to clear the market regardless of what debt managers are doing on the supply side.
Brad: So Treasury supply is competing for capital in a way it did not ten years ago.
Anshul: Yes, and that is why ownership matters alongside the amount of debt outstanding. A market with large price-insensitive buyers can absorb supply with relatively little adjustment. A market that relies on private capital may require a larger concession.
Brad: Which brings us back to my earlier point. Duration has to be held by somebody. If fewer price-insensitive investors are standing in the way, that somebody is increasingly a private investor demanding compensation.
Anshul: Fair. But even then, I wouldn't jump to the conclusion that supply is now the dominant force in the market.
Brad: Why not?
Anshul: Because this year provides a useful example. Most of the increase in longer-term Treasury yields has come from investors revising up the expected path of policy rates and the longer-run equilibrium rate. Term premium played a role, but expectations did most of the heavy lifting.
Brad: Is that just a monetary-policy story, or is something broader happening?
Anshul: Something broader. Investors are not only reassessing the supply of bonds. [TS3.1]They are also reassessing the demand for capital. Think about hyperscaler investment and AI infrastructure. That spending can affect expectations for productivity, growth and the economy's ability to sustain higher real rates. Those macro effects can matter more for Treasury yields than the financing choice itself.
Brad: So some of what looks like a supply story may actually be a growth story.
Anshul: Exactly. The issuance still adds to the amount of duration the market has to absorb. But investors also need to ask what the borrowing is financing and whether it changes growth, inflation or policy expectations.
Brad: I spend a lot of time talking to credit investors about the large private issuers who have so far seemed fairly insensitive to rates as their financing needs grow.
Anshul: I am not a credit guy, [TS4.1]but I think it is worth watching that sensitivity with the hyperscalers. If their issuance becomes large and persistent enough to affect the Treasury curve or the price of long-duration capital more broadly, financing conditions could start influencing the timing, maturity and scale of their borrowing.
Brad: So the interaction could run both ways: their investment plans affect the macro outlook, while the level and shape of rates affect how those plans are financed.
Anshul: And this is why I need to at least pretend to be a credit guy, since it is a real question as to whether hyperscaler issuance remains mainly a credit-market story or does it become a visible driver of the broader duration market.
Brad: It definitely matters, but there is also a general stock-versus-flow issue. The Treasury market is enormous, but it clears on the flow. New bonds have to find a home at every auction. Change how much comes as long bonds rather than bills and you change the marginal clearing price. That marginal price then reprices the outstanding amount.
Anshul: I agree with the mechanism. The question is persistence. In a market measured in tens of trillions, one quarter's issuance decision may not matter much on its own. A sustained change in issuance strategy can matter much more because investors start to price not just today's supply, but its expected path.
Brad: But debt managers do not control the deficit itself. They control how it is financed.
Anshul: That distinction is important. Whether Treasury issues bills or bonds changes who holds the risk and when it has to be refinanced. It does not eliminate the borrowing requirement. With deficits large and projected to remain large, the market still has to absorb a substantial amount of government debt over time.
Brad: For investors, that suggests a shorter issuance profile can support the long end now without resolving the longer-run fiscal question.
Anshul: That is why the initial market effect and the longer-run effect do not have to point in the same direction. Remember long-term rates are averages of years of short-term rates.
Brad: Let's move from theory to evidence. Treasury buybacks seem like a useful test. They don't change growth. They don't change inflation. They simply change how much duration the market has to absorb.
In fact, this may be the closest thing we have to a controlled experiment live in the market right now. The economic outlook and the deficit are unchanged. Treasury is altering the amount and location of duration available to the market. If we want to isolate the supply channel, this is a relatively clean place to look.
Anshul: I would agree with that. Buybacks operate through the channel we are debating. They can improve liquidity, remove less-liquid securities and reduce the net duration investors need to hold in the targeted maturity buckets.
Brad: Treasury recently increased the cap on a 10-20 year buyback operation to $6bn from $2bn and committed to future operations of at least $4bn. At the higher size, buybacks could absorb a very meaningful share of long-end issuance, potentially up to 40%.
Anshul: And the market reaction has been broadly consistent with the supply story. The sectors receiving the most direct support have tended to outperform. We've seen that in the 20-year sector and in parts of the swap spread market.
Brad: Which sounds like evidence that debt management works.
Anshul: It's evidence that debt management works in relative value. Where I'm more cautious is jumping from that observation to the conclusion that buybacks determine the outright level of 10-year or 30-year yields, which have gone the opposite direction of what Treasury likely hoped for since those actions.
Brad: But for investors, relative value isn't a consolation prize.
Anshul: I completely agree. In fact, that's probably one of the biggest takeaways from this debate. Macro may drive outright duration. Issuance can be decisive for curve trades, sector selection and relative-value opportunities.
Brad: But debt managers should care more about absolutes. I get why as well. In the US, annual interest expense is around $1trn and now exceeds defense spending. At today's debt levels, deficits are much more sensitive to interest rates, so even modest changes in funding costs can compound into meaningful fiscal consequences.
Anshul: And it’s more than just the government’s own interest bill. Treasury yields feed into mortgage rates, corporate borrowing costs and financial conditions more generally. That puts affordability in the conversation. Debt managers cannot set those rates, but they have a reason to avoid adding unnecessary pressure through poor market functioning or an issuance mix the market struggles to absorb.
Brad: Historically I agree that the objective is not to engineer a particular yield. It is to keep financing orderly and avoid paying more than necessary, but I am more skeptical recently.
Anshul: I don’t think that is necessarily true globally even if the results have been similar. Japan's issuance changes supported the affected sectors initially, but broader changes in fiscal policy expectations eventually pushed long-end yields higher. The policy helped, but it did not remove the macro risk.
Brad: For investors, that argues for distinguishing an outright duration view from a cross-market or curve view.
Anshul: Yes. A debt manager may not reverse a global selloff, but the issuance response can still determine which market or maturity outperforms within it.
Brad: So you are willing to grant my point on relative value, but still a bit of a holdout on absolute levels.
Anshul: That is a fair characterization.
Brad: Let me try one more real-life example. What about QE? Many people would argue that's the cleanest example of duration supply affecting yields.
Anshul: QE is strong evidence that duration matters. But QE did two things. It removed duration from the market and it signaled that policy rates would remain lower for longer. So it affected both term premium and rate expectations.
Brad: In other words, it probably overstates what debt management alone can achieve.
Anshul: That's how I'd think about it.
Brad: As we said earlier it is really hard to isolate these things. So we both have our views, but being the guy who spends his whole day watching Treasury markets, what are you looking at in the short-term to help score this debate?
Anshul: Three things. First, whether term premium is moving independently of policy expectations. Second, whether markets with less net duration supply consistently outperform. Third, whether auction performance and market liquidity show signs that investors are struggling to absorb supply.
Brad: And what would convince you that debt managers are succeeding?
Anshul: Better auction outcomes, stronger relative performance in sectors receiving relief and continued evidence that issuance changes are affecting market pricing. The buyback program is already providing some evidence along those lines.
Brad: So perhaps the answer is that debt managers cannot control long-term yields, but they can influence the price investors demand to hold duration.
Anshul: Exactly. Growth, inflation and policy expectations will usually determine the overall direction of yields. But issuance decisions can still be powerful drivers of relative performance across markets, sectors and maturities.
Brad: Which means investors need to pay attention to both. Macro may tell you where yields are headed. Supply may tell you where the best opportunities are. Thanks again for joining me today Anshul. Clients of Barclays Investment Bank can read more about this topic in our dedicated US Rates Research section on Barclays Live. Thanks for listening, and we'll see you next time on The Flip Side.
About the experts

Brad Rogoff
Global Head of Research
Anshul Pradhan
Head of US Rates Research
* We acknowledge and agree for Barclays to collect, use and otherwise process our/the Relevant Individual's Information in accordance with the Notice, other effective privacy terms and information processing terms agreed by ourselves/the Relevant Individual with Barclays, for the purposes set out therein, respectively.
* We acknowledge and agree that Barclays may disclose to any third party described in the Notice as a potential recipient of data outside mainland China our.the Relevant Individual's Information in accordance with the Notice, other effective privacy terms and personal information processing terms agreed by ourselves/the Relevant Individual with Barclays, and for the purposes set out therein, respectively.
I consent to my email address being used by Barclays to provide me with personalized advertisements on third-party websites and social media platforms, as described in our Privacy Notice.
An email was sent to you at the address provided. Complete your subscription by clicking the link provided to verify your email address.
Sorry there was a problem. Unfortunately your subscription to our newsletter has encountered an error.
In addition to the cookies we use on our website, we also use cookies and similar technologies in some emails and push notifications. These help us to understand whether you have opened the email and how you have interacted with it. If you have enabled images, cookies may be set on your computer or mobile device. Cookies will also be set if you click on any link within the email.
In addition to the cookies we use on our website, we also use cookies and similar technologies in some emails and push notifications. These help us to understand whether you have opened the email and how you have interacted with it. If you have enabled images, cookies may be set on your computer or mobile device. Cookies will also be set if you click on any link within the email.
In addition to the cookies we use on our website, we also use cookies and similar technologies in some emails and push notifications. These help us to understand whether you have opened the email and how you have interacted with it. If you have enabled images, cookies may be set on your computer or mobile device. Cookies will also be set if you click on any link within the email.
Please review and manage your email cookie settings below. For more information, please read our Cookie Policy. Please select 'Save and Subscribe' below to remember your email cookie preferences and subscribe to the newsletter.